
The cost of cutting corners on insurance
Johannesburg - Ongoing financial pressure is prompting many South Africans to look for quick ways to reduce their monthly expenses. Amid rising living costs and municipal tariff hikes, household budgets are under severe strain. Insurance is often one of the first expenses consumers consider cutting, downgrading, or cancelling entirely. However, while reducing cover may provide instant relief on a monthly statement, it can also expose households to significant long-term financial risks.
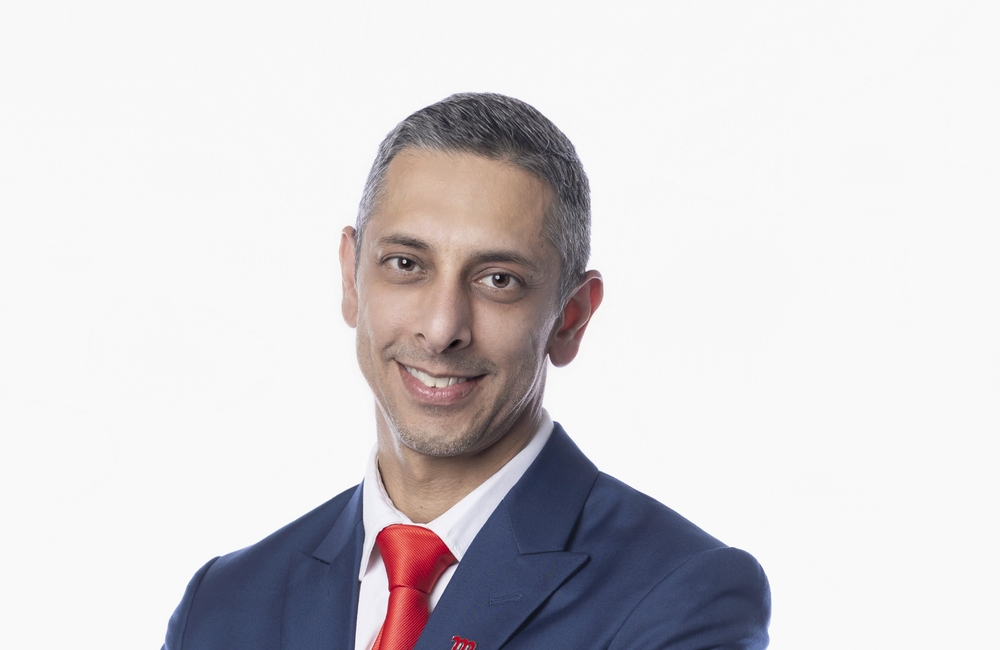
Dipesh Radia, Chief Commercial Officer at Momentum Insure explains that as weather events and other disruptions increase, insurance costs are rising too, adding to the financial strain many households are already under. "While it’s completely understandable that families are looking for breathing room in their budgets, viewing short-term insurance as a discretionary luxury rather than an essential financial safeguard introduces disproportionate risks."
When consumers reduce their cover without fully understanding the implications, they face the risk of underinsurance. If property or a vehicle is insured for less than its actual replacement value, any future claim may be paid out proportionally. This means a small monthly saving on premiums can leave a household exposed to massive, unexpected out-of-pocket expenses should an incident occur. While insurance is designed to absorb the financial impact of unpredictable events, an underinsured individual may find themselves responsible for a substantial shortfall.
Rather than cancelling insurance altogether, Radia encourages consumers to view it as a critical safety net that protects their long-term financial wellbeing. Managing insurance costs effectively requires a proactive partnership between insurers and clients, focusing on reducing risk and finding practical ways to lower premiums without compromising essential cover.
"Before making any drastic changes to a policy, consumers should engage directly with their broker or financial adviser. These professionals are equipped to help restructure policies to fit tighter budgets while ensuring that essential assets remain adequately protected,” he says.
There are several practical strategies consumers can implement to manage their premiums responsibly, suggests Radia. These include consolidating policies to combine home, contents, and vehicle insurance under a single provider which could unlock meaningful discounts.
Another way to reduce premiums is to choose a higher voluntary excess. While this can lower monthly insurance costs, it should only be considered if the consumer has sufficient savings set aside to cover the excess should they need to claim.
Reviewing the insured value of older assets, particularly vehicles that have depreciated over time, can help lower premiums by ensuring they are not overinsured.
Installing approved security systems, tracking devices, or smart water-shutoff valves lowers the overall risk profile, which may lead to lower premium rates.
“Saving a small amount today by eliminating or reducing insurance costs could cost significantly more tomorrow,” says Radia. “Making informed, calculated decisions about short-term insurance cover with the guidance of an adviser remains one of the smartest choices a consumer can make to safeguard their financial resilience.




 Insurance Biz proudly displays the "FAIR" stamp of the Press Council of South Africa, indicating our commitment to adhere to the Code of Ethics for Print and online media which prescribes that our reportage is truthful, accurate and fair. Should you wish to lodge a complaint about our news coverage, please lodge a complaint on the Press Council's website, www.presscouncil.org.za or email the complaint to enquiries@ombudsman.org.za. Contact the Press Council on 011 4843612.
Leave a Comment